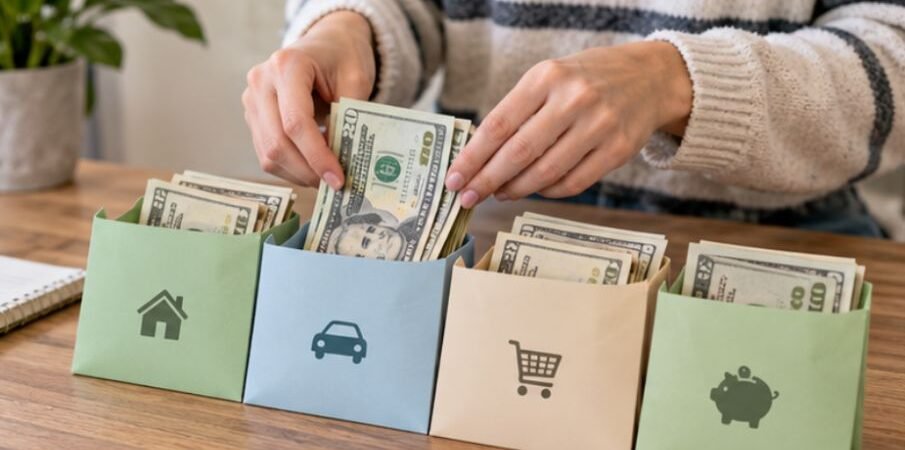
A budget that ends at zero can be a sign of control, not failure. In a zero-based plan, you decide where every dollar of monthly income will go before you spend it. Rent, groceries, debt payments, savings, investing, and fun money all get assignments until income minus planned outflows equals zero.
That is the central idea behind zero based budgeting for beginners: no money is left “unclaimed” on the plan. Your checking account does not have to fall to $0. The zero exists on the budget worksheet, not necessarily in the bank.
What Zero-Based Budgeting Actually Changes
Most people already have recurring bills, savings goals, and spending habits. The difference is that a zero-based budget forces you to make those choices deliberately instead of letting leftover cash disappear into miscellaneous purchases.
For households, monthly income is matched with planned spending, saving, investing, and debt repayment. Consumer.gov budgeting guidance describes a budget as a written monthly plan that compares what you make with what you spend. The Consumer Financial Protection Bureau also recommends looking back over several months so infrequent costs such as insurance, medical bills, school expenses, gifts, and vacations are not missed.
A simple framework like the 50/30/20 budget rule can also help beginners divide income between needs, wants, and savings.
That matters because “unexpected” spending is often predictable. A car registration due every year or a twice-yearly insurance premium may not arrive monthly, but it can still be converted into a monthly amount.
Personal zero-based budgeting also differs from the corporate version. Businesses may ask departments to justify expenses from scratch instead of rolling forward last year’s budget. Households use the same zero-from-the-start idea more simply: every dollar must support a current need, goal, or priority.
The Five-Step Setup That Works for Beginners
1. Start With Take-Home Income
Use the money that actually reaches your household after taxes, payroll deductions, and other withholdings. If your pay varies, build the budget around a conservative income estimate rather than your best month.
2. List Fixed, Flexible, and Periodic Expenses
Fixed expenses include rent and loan payments. Flexible expenses include groceries, gas, clothing, and entertainment. Periodic expenses include costs that arrive only a few times a year.
Colorado State University Extension’s spending-plan guidance recommends converting occasional costs into monthly savings amounts. If annual auto registration and maintenance total $1,200, for example, setting aside $100 a month turns a future bill into a planned expense.
3. Fund Necessities Before Preferences
Housing, basic utilities, food, transportation needed for work, minimum debt payments, insurance, and essential health costs usually come first. Then assign money to emergency savings, extra debt payments, retirement, and short-term goals.
The FDIC’s budgeting resources explain that a budget helps households track income, spending, and savings while making tradeoffs between needs and wants.
There is evidence that structured financial education can improve budgeting behavior. A 2025 FDIC evaluation of its “How Money Smart Are You?” resource found budget use among participants increased from 57% to 69% after the resource was introduced. That association does not prove budgeting alone caused the change, but it reinforces why financial educators treat budgeting as a core money-management skill.
4. Keep Assigning Until the Remainder Is Zero
Suppose monthly take-home pay is $4,500. A beginner budget might look like this:
| Category | Planned Amount |
| Rent | $1,500 |
| Utilities and phone | $300 |
| Groceries | $600 |
| Transportation | $400 |
| Insurance and health | $300 |
| Debt payments | $400 |
| Emergency and sinking funds | $400 |
| Retirement investing | $300 |
| Personal and fun money | $200 |
| Miscellaneous buffer | $100 |
| Total | $4,500 |
The final $100 is not “extra.” It already has a job as a buffer. If it is not needed, you can move it to savings or debt repayment.
5. Track and Adjust During the Month
Compare actual spending with planned amounts at least weekly. If groceries run $60 over budget, reduce another category by $60 or use an existing buffer.
Comparing your actual spending with your plan is easier when you track expenses automatically throughout the month.
Consumer.gov recommends reviewing spending and using what actually happened to improve the next month’s plan. The goal is accuracy, not perfection.
Three Beginner Mistakes That Make the Method Feel Too Strict
The first mistake is confusing “zero-based” with “spend everything.” Savings and investing are assignments too. Money moved to an emergency fund, retirement account, or future repair fund still has a job.
The second mistake is budgeting only regular bills. The CFPB’s spending assessment guidance advises reviewing several months of transactions so less frequent costs are captured. If birthdays, annual memberships, medical copays, and repairs never appear in the plan, the budget will repeatedly seem to fail.
The third mistake is making categories unrealistically small. Utah State University Extension’s financial wellness guidance recommends setting realistic expectations after tracking spending. Cutting restaurant spending from $300 to $0 overnight may look disciplined, but a sustainable reduction is often more useful.
What If Your Income Changes Every Month?
Freelancers, hourly workers, commission earners, and seasonal workers can still use zero-based budgeting. Start with a low-but-realistic baseline based on recent months and fund essentials first.
When additional income arrives, assign it in a preset order—for example, next month’s bills, emergency savings, high-interest debt, retirement, then discretionary goals. A separate income buffer can also smooth uneven months.
The objective is not to predict every paycheck perfectly. It is to decide what each new dollar should do once it arrives.
A Simple Test Before You Commit
Zero based budgeting for beginners may suit people who regularly wonder where their paycheck went, have several savings goals, are paying down debt, or want tighter control over discretionary spending. It may feel unnecessarily detailed if your finances are already highly automated and stable.
Try it for two full months before judging it. Month one exposes missing categories. Month two is usually more realistic because you are budgeting from actual behavior instead of guesses.
Frequently Asked Questions
1. Does zero-based budgeting mean I should keep $0 in my checking account?
No. It means every dollar of income is assigned in your budget. You can keep a checking cushion, but label it intentionally rather than treating it as unplanned money.
2. Should savings count as an expense in a zero-based budget?
Yes. Savings, investing, emergency funds, and sinking funds are planned uses of income. Assigning money to future goals is one of the method’s strongest features.
3. What happens if I overspend one category?
Move money from another category or use a planned buffer. The budget should stay balanced as circumstances change rather than ignoring the overage.
4. Can zero-based budgeting work with irregular income?
Yes. Use a conservative income baseline, cover essentials first, and create rules for assigning extra income when it arrives.
Make Zero the Most Useful Number in Your Budget
The appeal of zero-based budgeting is not the arithmetic; it is the decision-making. Instead of reaching the end of the month and asking where the money went, you decide where it should go before spending begins.
For beginners, the best version is not the most detailed spreadsheet. It is the plan you can update consistently, with realistic categories, room for irregular expenses, and savings treated as a priority rather than an afterthought. Start with your next paycheck, assign every dollar a purpose, and let the budget reflect your real life rather than an idealized one.